Most manufacturers know their wage bill to the penny; what’s harder to pin down is the true cost of an hour’s productive work, the figure that actually belongs in a product pricing exercise or a job quote.
Employer National Insurance contributions (NICs), pensions, holiday pay, overtime and agency cover all push the true price of an hour’s work well above the headline rate. Profit margins can silently disappear in the gap between that headline rate and labour’s true cost. What’s more, the 2025 increase in employer NIC and the April 2026 increase in the National Living Wage have widened that gap at a time when more than 55,000 manufacturing job vacancies are maintaining upward pressure on wages. For finance and operations teams facing labour decisions, the crucial question is whether their cost figures are accurate enough to act on.
This guide breaks down what labour costs include, the categories worth tracking separately, the formulas that matter and how these figures feed into costing, pricing and longer-term decisions.
What Are Labour Costs?
Labour costs refer to all the expenses related to employing the people who make a manufacturer’s products and keep production running. In addition to basic wages, employers must fund NICs, pension contributions, paid holidays and other costs associated with adding someone to the payroll.
For manufacturers, those costs are typically split between two groups: the workers who physically make goods and the people who support production behind the scenes. Together, these labour costs often represent one of the largest lines in a manufacturer’s accounts, and every percentage point shaved off can improve margins.
Key Takeaways
- Accurate labour-cost tracking has become increasingly important as increases in employer National Insurance contributions and the National Living Wage push UK labour costs higher.
- Finance teams split labour into categories, such as direct and indirect or fixed and variable, to better understand how to control costs.
- Specific measures, such as the fully burdened hourly rate or labour cost as a percentage of sales, support more profitable costing, pricing and benchmarking strategies.
- AI-powered analytics can transform labour cost data into early warnings by spotlighting overtime patterns, agency spend anomalies and productivity shifts before they erode margins.
Manufacturing Futures: Tomorrow's Vision
Labour Costs in Manufacturing Explained
Manufacturers peer through more than one lens to develop a full picture of their labour costs. Finance teams often focus on labour’s relationship with output, asking questions like “Can we trace this cost to a specific product?” or “Does it fluctuate with production volume?” These questions determine how costs are recorded and, ultimately, how they shape product prices. Production teams, on the other hand, focus more on how each cost contributes to the manufacturing process, so as to quantify the value of indirect costs like routine equipment maintenance and quality control checkpoints. A manufacturer’s approach to controlling costs typically reflects its priorities: a small-batch maker that relies on skilled manual labour interprets its cost figures differently from a plant running fully automated lines.
UK manufacturers need a clear-eyed view of their labour costs when making long-term plans. In the UK, reducing permanent headcount is a slow, costly and heavily regulated process; staffing levels cannot simply be adjusted when demand softens. The higher the fixed labour costs, the harder it becomes to ride out a dip in orders. Good labour cost management helps manufacturers understand how much flexibility they have when demand or costs shift and how to balance the mix of people and machines they rely on.
What Is Labour Cost Percentage?
Labour cost percentage is one of the key metrics manufacturers use to gauge labour as a share of a bigger figure, usually total manufacturing cost or total sales. It adds context to raw pound amounts, allowing managers to weigh labour costs against output or total expenses and benchmark performance relative to earlier periods or industry norms. If the percentage drifts upwards, managers can act to reduce costs or increase efficiency before rising labour costs eat into long-term profitability.
Direct vs. Indirect Labour Costs
Every labour cost in a factory falls into one of two camps: direct costs, which can be tied to a specific product, and indirect costs, which can’t. Because the latter group can’t be traced to any one product, finance teams spread it over everything the factory makes as overhead. How they calculate and allocate that overhead sets each product’s true cost, and, in turn, shapes its price.
Direct Labour Costs
Direct labour costs comprise the wages and on-costs associated with the people who physically make the product, such as machine operators and assembly-line workers. Because their time can be traced to a specific unit or batch, these costs sit in inventory value until the goods sell, at which point they become part of the cost of goods sold (COGS). Direct labour typically rises and falls with production volume, so it is a variable cost in most operations.
Indirect Labour Costs
Indirect labour costs include the people who don’t work on any single product, such as supervisors or maintenance engineers. Because their pay can’t be attributed to one unit, it is included in the manufacturing overhead pool and allocated across products using an absorption rate.
Fixed vs. Variable Labour Costs
As seen in the preceding section, some labour costs depend on output, and others remain relatively constant month after month. Understanding each cost category and what managers can and can’t control matters for budgeting, break-even calculations and capacity analysis. For example, if a manufacturer is entering the slow season, a plant manager can scale back overtime scheduling and temporary hires, but likely can’t change budgets for administrative salaries.
Fixed Labour Costs
Fixed labour costs stay the same regardless of how many products the factory makes, at least within a normal range of activity. Salaried supervisors and permanent maintenance staff, for example, fall into this group, since they draw the same pay whether the line runs at full speed or sits idle half the time. In the UK, employment law tends to reinforce that fixity, since cutting permanent head count comes with redundancy costs and notice periods.
Variable Labour Costs
Variable labour costs rise and fall with production. Wages for hourly production workers climb when the line is busy and ease when it slows, as do overtime and agency cover. Manufacturers that rely on a higher share of variable labour have more room to manoeuvre when demand dips, though a heavy reliance on variable workers can limit profits when demand surges and manufacturers are left paying higher overtime rates. Scenario modelling with AI can help finance teams test different fixed-variable mixes against demand forecasts, projecting how each structure would perform if orders rose by, say, 20%, or fell by the same percentage.
Why Do Manufacturers Need to Calculate Labour Costs?
Labour cost feeds into nearly every one of a manufacturer’s commercial decisions, so its accuracy is essential. Take pricing, for instance. Prices based only on wages, instead of true labour cost, leads to thin margins, or worse, losses, on every unit sold. Labour cost also flows into accounting figures, such as inventory valuation and COGS, so a costing error could distort the books.
Accurate labour costs also feed into long-term strategy. A finance team weighing whether to invest in more efficient machinery should first understand the real productivity increases and labour cost reductions it would entail; without those numbers, ROI calculations will be off base. When production managers want to expand the workforce, a clear view of the true costs, on-costs included, helps them balance growth with short-term profitability. Calculating per-unit labour costs also gives managers a benchmark for productivity that is grounded in real money. AI-powered systems can apply this analysis to help teams identify which product lines, shifts or facilities are driving costs up, without incurring hours of manual number-crunching.
Factors That Affect Labour Costs
Several forces can push a manufacturer’s labour costs up or down over time, and in the UK, many costs are set by statute. Understanding each factor helps finance and human capital management teams differentiate between what they can and cannot control.
By law, employer NICs are set at 15% for most workers; minimum pension contributions start at 3% but vary by scheme. Meanwhile, the National Living Wage climbs most years, rising 4.1% in April 2026 to £12.71 an hour for most adults. Paid leave adds another layer, as full-time workers on the statutory minimum are entitled to 5.6 weeks off. Part-time workers are also entitled to paid leave, proportional to their average working week. All of these create mandatory labour costs that don’t translate to output.
Then, there are the market pressures. According to a 2025 survey by Make UK, there are more than 55,000 job vacancies in the manufacturing sector, and four out of five firms have been attempting to fill them for at least three months. Respondents said their top barriers to recruiting were a lack of the right technical skills (62.9%), the right qualifications (22.9%) or a sufficient number of applicants (20%). This tight labour market forces manufacturers to pay premium rates to attract and keep skilled workers with specialised expertise, such as CNC machinists and maintenance engineers. Manufacturers that can’t fill those slots must lean on overtime and agency staff to cover the shortfall, which pushes costs higher.
Even sickness absence carries a cost, including continued pay and the overtime or temporary cover required to keep the line moving. A Chartered Institute of Personnel and Development (CIPD) analysis puts average absence at 9.4 days per employee in 2025 (the highest in more than 15 years) and 4.1% of working time lost. Agency staff can plug gaps fast, but leaning on them too heavily means paying a mark-up over permanent rates and missing out on opportunities to build institutional knowledge. Integrated systems that use AI to analyse absence data, agency spend and production output can help managers spot subtle shifts when temporary cover starts becoming a structural cost, rather than an occasional fix.
How Do You Calculate Total Labour Cost?
Total labour cost is the full cost of the workforce over a set period, incorporating all wages and on-costs. For a past period, the figures are generally already in payroll and pension records. That means the main job is making sure everything gets included, even statutory costs, uniforms and training. Most manufacturing accounting software and ERP systems handle these calculations automatically, and AI-enhanced systems can signal when changes in overtime patterns, absence or on-cost assumptions push rates outside expected ranges.
The most useful number for day-to-day costing is the fully burdened rate, which quantifies the cost of one productive hour of a worker’s time. To get it, use the following formula:
Fully burdened hourly rate = Total annual employment cost / Productive hours available
First, find total annual employment cost by adding a worker’s on-costs to their gross pay for the year. Then, divide that sum by the hours they are available to work, after subtracting holiday leave and typical absences. The result lands well above the gross hourly wage; it should be the baseline used in product costing and job quote calculations.
Calculating Direct Labour Costs
Direct labour cost per unit considers only the hands-on work that goes into a single product. It is often the first figure that feeds product costing and pricing, and it can be calculated in the following three steps:
-
Determine the direct hourly labour rate. For accurate costing, this should be the fully burdened rate (base wage plus on-costs, expressed hourly). For products that pass through workers on different pay or shift patterns, use a weighted average that reflects the actual mix:
Direct hourly labour rate = Base hourly wage + Direct labour on-costs
-
Calculate hours worked per product. Find the average time it takes to make one unit. These hours can come from production logs, an ERP system or stopwatch time studies. They should include every stage of hands-on work, from machine setup at the start to final inspection at the end. If products are made in batches, time should be apportioned accordingly per unit. If a 50-unit batch takes 2 hours, for example, each unit would be allocated 0.04 hours (2 hours / 50 units).
Hours per unit = Total production hours / Units produced
-
Tabulate total direct labour cost per unit. Multiply the direct hourly labour rate by the hours per unit. The result is the direct labour cost for each unit, which pricing teams can combine with materials and overhead to calculate the full product cost:
Direct labour cost per unit = Direct hourly labour rate x Hours per unit
Calculating Total Manufacturing Labour Costs as a Percentage of Total Manufacturing Cost
Total labour cost can be a useful measure on its own, but looking at it in isolation can hide important trends. Rising labour costs might signify inefficiencies, but might also be a sign of success if output increases proportionally or faster. Regularly calculating labour as a percentage of total manufacturing cost tells managers what portion of production costs should go to labour. Any noticeable change in that percentage should be investigated.
To calculate it:
- Sum up total manufacturing labour costs. Add together every labour cost tied to production for the period: direct wages, indirect labour, on-costs and overtime pay. Unlike the stripped-back per-unit direct rate, this total takes in support staff (supervisors and maintenance engineers) as well as the people on the line.
-
Add together direct materials, direct labour and manufacturing overhead. Combine raw material expenses with direct labour and overhead costs, such as factory rent, utilities, supplies and equipment depreciation:
Total manufacturing cost = Direct materials + Direct labour + Manufacturing overhead
-
Calculate labour cost percentage. Divide total manufacturing labour costs by total manufacturing cost and multiply by 100. Be sure every figure covers the same period:
Labour as a percentage of total manufacturing cost = (Total manufacturing labour costs / Total manufacturing cost) x 100
Calculating Total Labour Costs as a Percentage of Total Sales
Measuring labour against sales shows how much of each pound of revenue goes towards people. It demonstrates whether the workforce is generating enough to cover their own costs and how much is left over for everything else the business must pay:
- Determine total labour costs. Pull the full cost of the workforce for the period from payroll and accounting records. Be sure to include everyone whose pay affects the bottom line, not just production. Admin, sales and management all count.
- Add together your total sales. Total sales, or net revenue, is the income from goods sold, often taken from the top line of the income statement. For a pure manufacturer, that’s operating revenue, so exclude one-off items, such as the sale of an asset.
-
Calculate labour cost percentage. Divide total labour costs by total sales and multiply by 100:
Labour cost percentage = (Total labour costs / Total sales) x 100
Example Labour Cost Calculations
To see how the three calculations work in practice, take King Colin’s Components, a fictional manufacturer of stainless steel brackets in Yorkshire. Each month, the owner, Colin, runs the numbers for one product and also for the business as a whole:
-
Direct labour cost per unit. The most popular bracket passes through two operators. Their fully burdened rate (base pay plus NIC, pension and holiday cover) works out to £20 an hour, averaged for both operators, and the bracket takes 0.3 hours of hands-on time.
Direct labour cost per unit = £20 x 0.3 = £6 per bracket
-
Labour as a percentage of total manufacturing cost. Colin totals production costs for a month: £58,000 of manufacturing labour, £132,000 of direct materials and £40,000 of manufacturing overhead. That brings total manufacturing cost to £230,000:
Labour as a percentage of total manufacturing cost = (£58,000 / £230,000) x 100 = 25.2%
-
Labour as a percentage of total sales. For the whole business that month, Colin’s total labour bill, including admin and sales staff, is £82,000, against sales of £360,000:
Labour cost percentage = (£82,000 / £360,000) x 100 = 22.8%
The three figures tell Colin different things: £6 of labour sits in every bracket, labour makes up about one-quarter of what it costs to make the goods and nearly 23p of every sales pound goes to workers. Read together, they give Colin a baseline to track over time, especially as labour costs rise. If costs tick up and revenue stays stagnant, he may need to review staffing levels or raise prices.
Four Tips for Lowering Labour Costs
Because labour costs are substantial and highly regulated, cutting them takes time and care. You especially don’t want to lose the things that keep customers coming back. Targeted steps, such as the following four measures, tend to work well.
-
Optimise Staff Scheduling and Reduce Overtime
Leaning on overtime week after week quietly inflates the wage bill, but overstaffing also cuts into margins. Digging into why overtime keeps cropping up, then matching staffing levels to real demand, usually trims costs appropriately. The root cause of staffing issues might be a machine prone to breaking down or materials delayed in the supply chain, not a genuine shortage of hands. AI-powered scheduling tools can help by analysing production schedules, employee availability and skill sets to recommend staffing levels that balance labour needs against costs. As these systems learn from historical patterns, they can spot when schedules are likely to lead to excess overtime and offer corrections before shifts are posted.
-
Identify Automation and Technology Opportunities
Automating repetitive tasks can help a manufacturer grow output without adding head count. The right technology moves people away from mundane or repetitive tasks, like data entry, and into work that needs judgement and skill. On the planning side, AI-driven forecasting can help managers match staffing to actual production demand, and ERP modules that link production, scheduling and payroll data show managers exactly where labour is wasted. AI can also detect anomalies, such as rising agency spend or scrap on one line, before they put a crimp in the bottom line.
-
Cross-Train Workforce to Increase Utilisation
Training people to perform more than one role leads to a more flexible operation. When a skilled operator is off, a cross-trained colleague can step in, avoiding agency cover or a halted line. In a tight labour market, building skills in-house also gives people a reason to stay. Respondents to CIPD’s “2024 Resourcing and Talent Planning” survey chose “increased focus on retaining talent” and “increased training” as their top two resourcing and talent practices. Nearly all respondents (95%) consider upskilling existing employees to fill hard-to-recruit positions.
-
Avoid the Following Mistakes
Some savings tactics can cost more than they save. The following tactics may look tempting on a spreadsheet but tend to backfire:
- Lowering staff wages: Cutting pay is a quick way to lose people. In a competitive market, recruitment and training bills for replacements can quickly offset any savings.
- Reducing hours across the board: Blanket cuts to contracted hours can breach agreements and invite claims. And even if that wasn’t the case, remaining employees will likely be overloaded. That leads to production bottlenecks and missed deadlines.
- Cutting quality corners: Trimming inspections or the staff who run them may save a little now but can cost a lot later in terms of increased scrap, rework and returns, not to mention lost trust. The cost of fixing quality problems frequently exceeds the savings achieved by the cuts.
Manage and Monitor Labour Costs with NetSuite for Manufacturing
Getting labour costs right requires accurate, current data. Paper time sheets that reach the accounts as a lump sum days later won’t cut it as manufacturers scale. NetSuite Manufacturing ERP Software brings shop-floor labour figures, work orders and production data into one system, connecting the hours a worker logs with the rest of the job’s costs and inventory data.
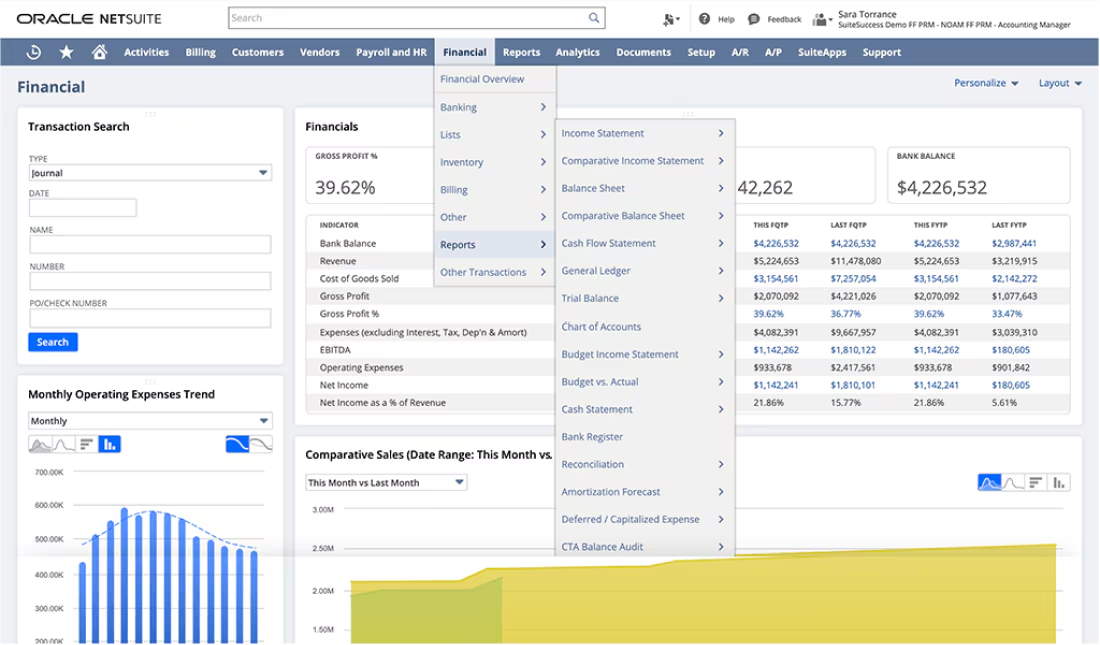
NetSuite cloud manufacturing accounting software then automatically applies those hours (costed at fully burdened rates with NIC and pension on-costs) to the general ledger and COGS. Customisable, real-time dashboards display the numbers that matter to each user, such as labour cost per unit or labour as a share of manufacturing cost, automatically highlighting variances or outliers as they happen. This data also feeds into NetSuite’s AI-powered analytics, which can then identify patterns, such as which shifts or product lines are causing overtime, or catch cost trends before they erode margins. With Ask Oracle, managers can query labour data conversationally and get quick answers that are grounded in live data through questions like “What’s our labour cost percentage this month, compared to last month?”
NetSuite’s Financial Dashboard
Managing labour costs requires looking closely and calculating with care. Once you account for what’s hidden under headline wages, you can track costs per unit to see how labour expenses compare to total production costs or sales to paint a clearer picture of where the money goes. For UK manufacturers facing a skills shortage and a higher National Insurance rate and wage floor, that clarity makes it possible to protect margins without cutting the features that help the business stand out from its competition.
Manufacturing Labour Costs FAQs
How do you calculate labour cost in manufacturing?
Start with the direct hourly labour rate (gross hourly pay plus on-costs, such as employer National Insurance and pension contributions), then multiply that rate by the average hours it takes to produce a single unit to get the direct labour cost per unit. For a whole-business view, accountants can also assess labour costs as a percentage of total manufacturing cost or total sales.
What is a good percentage for labour cost in manufacturing?
There is no single right number, because it swings according to how automated and how labour-intensive a business is. A highly automated commodity plant might have labour costs below a quarter of total manufacturing cost, while a boutique handmade-furniture manufacturer’s labour costs will likely run higher. Most manufacturers compare their labour cost percentage to industry or internal benchmarks, and watch to see if it stays steady, improves or creeps up over time.