Overhead can quietly cut into a manufacturer’s profits, as indirect costs (utilities, maintenance, rent, supervision, insurance) eat up a large portion of a business’s budget. Overhead isn’t connected to specific products, but it influences decisions from product pricing to factory layouts. For UK manufacturers, rising employer NICs, volatile energy prices, business rates, and other persistent cost pressures mean that sound overhead management can make the difference between healthy profits and chronic losses.
This guide breaks down manufacturing overhead, how to calculate it and what manufacturers can do to control it.
What Is Manufacturing Overhead?
Manufacturing overhead refers to the indirect costs of operating a production facility: the expenses necessary to keep the factory running but not directly traceable to specific products. Also known as factory overhead or production overhead, these costs include utilities, facility rent, equipment depreciation and wages for support staff who are not hands-on in producing products.
Manufacturers typically track three main expense categories: direct materials, direct labour and overhead. The first two tie directly to products. Raw materials become part of finished goods and wages pay for the workers who convert the materials into products. Overhead covers nearly everything else, including the electricity powering machines, maintenance keeping them running, supervisors coordinating production and business rates levied on factory premises.
Key Takeaways
- Manufacturing overhead includes all indirect production costs not traced to specific products, such as utilities, rent, maintenance and supervisory and support labour.
- Overhead is allocated to products through the overhead absorption rate, a ratio derived from direct activity measures like labour hours or machine hours.
- Monitoring and analysing overhead supports pricing and forecasting and guides lean manufacturing processes that improve efficiency.
- Overhead reduction strategies range from quick wins like energy management and aligning labour with demand to longer-term investments in automation and digital systems.
Manufacturing Futures: Tomorrow's Vision
Manufacturing Overhead Explained
Manufacturers track overhead because it represents a large portion of total production expense. How a company handles overhead has a direct effect on margins and competitiveness. For UK manufacturers specifically, overhead carries distinctive weight. Despite government efforts to bring down energy costs, for example, electricity prices remain elevated relative to some European competitors. Business rates add property-based overhead costs, and the April 2025 employer National Insurance contribution increase to 15% raised labour costs.
All overhead costs fall into one of three categories: fixed, semi-variable or variable.
Fixed Manufacturing Costs
Fixed manufacturing overhead remains the same regardless of production volume. For example, rent, business rates, insurance premiums and manager salaries don’t typically fluctuate from one month to the next, whether the factory is operating at 40% of capacity or 90%. This stability makes for predictable budgeting. But when production volume falls, the share of each sale that must go towards overhead, the overhead per unit, rises even though underlying costs have not changed.
Semi-Variable Manufacturing Costs
Semi-variable costs have two components: a constant base cost and variable charges tied to usage or volume. Machinery maintenance is a common example, as many manufacturers pay a flat fee for a service contract and scheduled inspections, plus variable costs for additional components and repairs that increase with higher operating hours. Understanding these thresholds helps manufacturers run break-even analyses and build more accurate budgets when planning production schedules.
Variable Manufacturing Costs
Variable manufacturing overhead rises and falls in concert with production activity. Utilities consumed by running machines, indirect materials used in production, and scrap disposal costs all fluctuate as output increases or decreases. These costs should be considered in every pricing decision and margin analysis.
Manufacturing Overhead Costs
Manufacturing overhead covers a wide range of costs that can vary by company, facility and even individual production lines. A small contract manufacturer may carry relatively light overhead, while a larger operation with owned premises and extensive equipment can see overhead take up a much larger portion of its total production costs. The most common overhead costs are:
- Indirect labour: Covers all wages and employment costs for support staff, such as supervisors, quality inspectors, maintenance technicians, warehouse staff and health and safety workers.
- Indirect materials: Consumables used in production that aren’t linked to individual products, including lubricants, cleaning supplies, cutting fluids, safety equipment and tooling components.
- Rents, leases, mortgages and utilities: Facility costs, such as monthly rent or mortgage payments, electricity, gas, water and business rates. Many of these are fixed and must be paid year-round, even when production slows.
- Factory supplies: Items that keep operations running but don’t directly enter production, such as packaging materials, office supplies for the factory floor and break room equipment or staff amenities.
- Maintenance and depreciation: Includes scheduled servicing, emergency repairs and the gradual loss of value in machinery and equipment over time. Accounting standards require depreciation to be allocated on a systematic basis over an asset’s useful life.
- Regulatory costs: Compliance-related expenses, such as environmental permits, health and safety activities, product testing, and, for manufacturers selling in EU and UK markets, UKCA and CE markings.
- Taxes and insurance: Includes property taxes, mandatory Employers’ Liability insurance, public and product liability coverage and sector-specific levies such as the UK Emissions Trading Scheme, which covers the heavy industry, power and aviation sectors.
Why Should You Track Manufacturing Overhead?
Accurately tracking overhead costs helps manufacturers set product prices that are “just right”: high enough to cover production costs and support profitability, but not so high that they risk pushing customers to competitors. Tracking overhead also gives manufacturers reliable data with which they can manage costs to achieve lean overhead. The same data feeds into expense projections, financial targets, production budgets and capacity planning. Timely overhead data lets manufacturers make strategic adjustments quickly, before profits are hit.
Overhead visibility also helps reveal inefficiencies, and AI-powered anomaly detection can accelerate this, identifying cost variances before they compound. If utility costs are climbing, that might justify investing in more efficient equipment, while a spike in repair bills could mean it’s time to rethink maintenance schedules. Key performance indicators (KPIs), such as overhead rate and cost per unit, give manufacturers a baseline to measure progress against.
Calculating Manufacturing Overhead
To calculate overhead, start by summing all indirect costs for a given period:
Total manufacturing overhead = Indirect labour + Indirect materials + Utilities + Rent and rates + Depreciation + Maintenance + Regulatory costs + Taxes and insurance + Other indirect costs
Total overhead can then be allocated to products using a predetermined rate. This rate, called the overhead absorption rate (OAR), is calculated by dividing total budgeted overhead by a chosen allocation base. The allocation base should tie to a production metric so that the OAR for each unit of production reflects its actual cost as closely as possible. For example, the OAR for a monthly electricity bill might tie to the number of hours factory machines were in operation that month: a measure that can further tie to specific products through the month’s production volume. The allocation base acts as a consistent, measurable proxy for distributing overhead across production, using the formula:
Overhead absorption rate = Overhead costs / Allocation base
Choosing the right allocation base depends on how the facility operates. Labour hours make sense for labour-intensive work where overhead loosely follows time spent. Machine hours are a better fit when automation drives most of the cost. For single-product shops or highly standardised lines, units produced might work. Pick a base that matches how overhead actually is consumed.
To calculate the overhead cost per unit, multiply the rate by the chosen allocation base. While this single calculation seems straightforward, as shown in the example below, many companies use accounting software to quickly switch between allocation bases for different product lines or facilities. This flexibility gives finance teams more targeted insights when setting prices and analysing margins.
Example Manufacturing Overhead Calculation
A furniture manufacturer wants to calculate overhead cost per unit for their tables. First, they tally their indirect costs for the month:
- Utilities (electricity and gas): £18,000
- Equipment depreciation: £12,000
- Maintenance and repairs: £8,500
- Indirect wages (supervisors, quality inspectors, warehouse staff): £42,000
- Rent and business rates: £15,500
- Total monthly overhead: £96,000
This manufacturer chooses direct labour hours as their allocation base because labour represents the majority of time and expenses incurred while producing these tables. This month, workers logged 12,000 hours.
Overhead absorption rate = £96,000 / 12,000 hours = £8.00 per labour hour
If producing one dining table requires 4 labour hours, the overhead cost per table is:
Overhead per unit = 4 hours × £8.00 = £32.00 overhead per table
The manufacturer can then add this £32.00 to direct labour and material costs to determine the total production cost and set prices accordingly.
Accounting for Manufacturing Overhead
Manufacturing overhead is accounted for differently than direct costs. Because overhead rates are typically set using budgeted figures and estimated allocations, the amount absorbed into product costs rarely matches the actual overhead incurred. When production exceeds expectations, more overhead gets absorbed than was actually incurred (called over-absorption) and the excess is credited to the profit and loss account, typically as an adjustment in cost of sales. When activity falls short, under-absorption occurs and the shortfall reduces reported profit. Generally, under-absorption is more common, especially during unexpected slow periods, and can significantly affect gross margins.
UK GAAP, specifically FRS 102, requires all normal manufacturing overhead to be absorbed into product costs for external financial statements. Abnormal costs, such as the cost of idle capacity beyond usual levels, may be excluded and expensed in the period. But, internally, many manufacturers use marginal costing instead, treating fixed overhead as a period expense to shape one-off pricing, make-or-buy decisions, break-even analyses and contribution margin reporting. Either way, the gap between absorbed and actual overhead is worth reviewing regularly. Big variances often point to efficiency changes, creeping costs or budget assumptions that need revisiting.
Strategies for Lowering Manufacturing Overhead
Cutting overhead means targeting the costs that move the needle. Some categories, including rent, rates and depreciation are locked in for the short term and only shift with bigger moves like renegotiating a lease. Other strategies, such as reducing energy consumption or improving indirect labour scheduling, offer quicker wins. The following strategies cover both.
-
Improve Supplier Relationships
Consolidating the supplier base and building longer-term partnerships can unlock bulk discounts and preferential treatment for deliveries and payment terms. However, in the post-Brexit environment, where supply chains stretch further and move through more checkpoints, it pays to keep a few backup suppliers in the mix.
-
Digitise Operations
Paper-based processes carry hidden costs, such as increasing labour costs as staff manually collect data, file documents and reconcile records. Deploying an ERP system with automated shop-floor data collection, inventory tracking, financial reconciliation and quality management reduces indirect labour expenses and manual errors. Cleaner data also feeds into more reliable cost allocation, KPI analyses and financial reporting.
-
Redesign Floor Space
A well-designed plant layout puts workers closer to equipment and materials to reduce wasted movement, saving time and money. In the UK, where business rates are calculated per square metre of factory floor, eliminating wasted space can trim occupancy costs. Even if a manufacturer is locked into their current location, renting out unused floor space to other businesses can help offset fixed overhead, an approach covered in more detail below.
-
Lower Energy Consumption
Energy is one of the most volatile overhead costs. Electricity prices bounced between a 21% year-over-year drop in May of 2024 to an 8% YoY increase in September 2025, according to the Office for National Statistics. Practical saving measures include scheduling high-energy processes during off-peak periods and investing in efficient lighting and HVAC systems. For manufacturers with a wide range of equipment, sub-metering consumption by machine or production area can identify inefficiencies. AI-powered energy monitoring can take this further, detecting efficiency degradation and recommending adjustments before waste accumulates. Variable-speed drives can trim usage without affecting output. For energy-intensive businesses, participation in climate change agreements can also reduce Climate Change Levy obligations.
-
Refine Scheduling
Aligning work shifts with actual demand reduces both idle time and unbudgeted overtime. Scheduling tools, many of which use advanced analytics and AI, can help match shifts to forecasted workloads to better balance staffing levels during quiet periods and peaks. And when schedules are predictable, staff tend to stick around longer, which saves on recruiting and training.
-
Rent Excess Factory Space
Manufacturers with underutilised capacity can offset their overhead by renting idle floor space to other businesses. This can be especially beneficial for seasonal businesses with fixed year-round costs, such as a manufacturer of Christmas items renting out space during the off-season to cover its year-round insurance and tax payments. However, manufacturers should review lease terms, planning permissions, security arrangements and insurance implications before seeking tenants.
-
Adopt Lean Manufacturing Processes
Lean manufacturing minimises waste without sacrificing productivity through techniques like 5S (sort, set in order, shine, standardise, sustain), value stream mapping, just-in-time inventory management and kaizen practices. When properly implemented, lean principles can reduce material usage, handoffs, motion, idle time, and, ultimately, overhead. Shifting a plant or company to a continuous improvement culture can take time but often brings ongoing benefits as new efficiencies are folded in.
-
Use Predictive Maintenance and Smart Sensors
Fixing equipment after it fails is expensive and disruptive. Predictive maintenance uses Internet of Things sensors (temperature, vibration, acoustic emissions) to constantly monitor machinery conditions. Machine learning AI models trained on this data learn to identify degradation patterns specific to each machine, detecting problems before they cause breakdowns. This proactive approach reduces unplanned downtime and extends equipment life, especially for ageing machinery. The steady stream of performance data also helps factory teams justify new investments and direct resources where they’ll have the biggest benefits when overhauls become necessary.
-
Automate Manual Tasks
Automation trims indirect labour costs while making production more consistent. Robotic process automation, for example, can handle repetitive admin (purchase orders, invoice matching) without the errors of manual data entry. AI-powered agents go further, reviewing expense reports for policy violations, identifying procurement savings and resolving routine exceptions without human intervention. On the shop floor, automated systems mean less rework and higher output. As NICs and minimum wage keep climbing, the ability to scale throughput without adding headcount becomes increasingly valuable.
-
Optimise Materials
Reducing material waste directly lowers overhead tied to disposal, storage and handling, as well as direct material costs. Tightening tolerances and improving cutting patterns can reduce scrap. Manufacturers can work with their engineers to identify longer-lasting or lower-cost alternatives for indirect materials like lubricants, tooling and consumables. If switching isn’t an option, better inventory management can reduce carrying costs and obsolete inventory write-offs.
-
Upgrade Software and Equipment
Outdated software and equipment can increase overhead in invisible ways. Their inefficiencies often require manual workarounds, for example, and their age comes with higher maintenance costs. On the production side, replacing outdated machinery can create a more energy-efficient and lower-maintenance shop floor. On the office side, ERP platforms can replace fragmented systems with integrated automation for time-consuming processes such as supply chain management and financial reporting. In either case, upfront capital investments can be significant, but the value of long-term overhead savings and quality improvements usually justify the cost.
Monitor and Optimise Overhead Costs with NetSuite
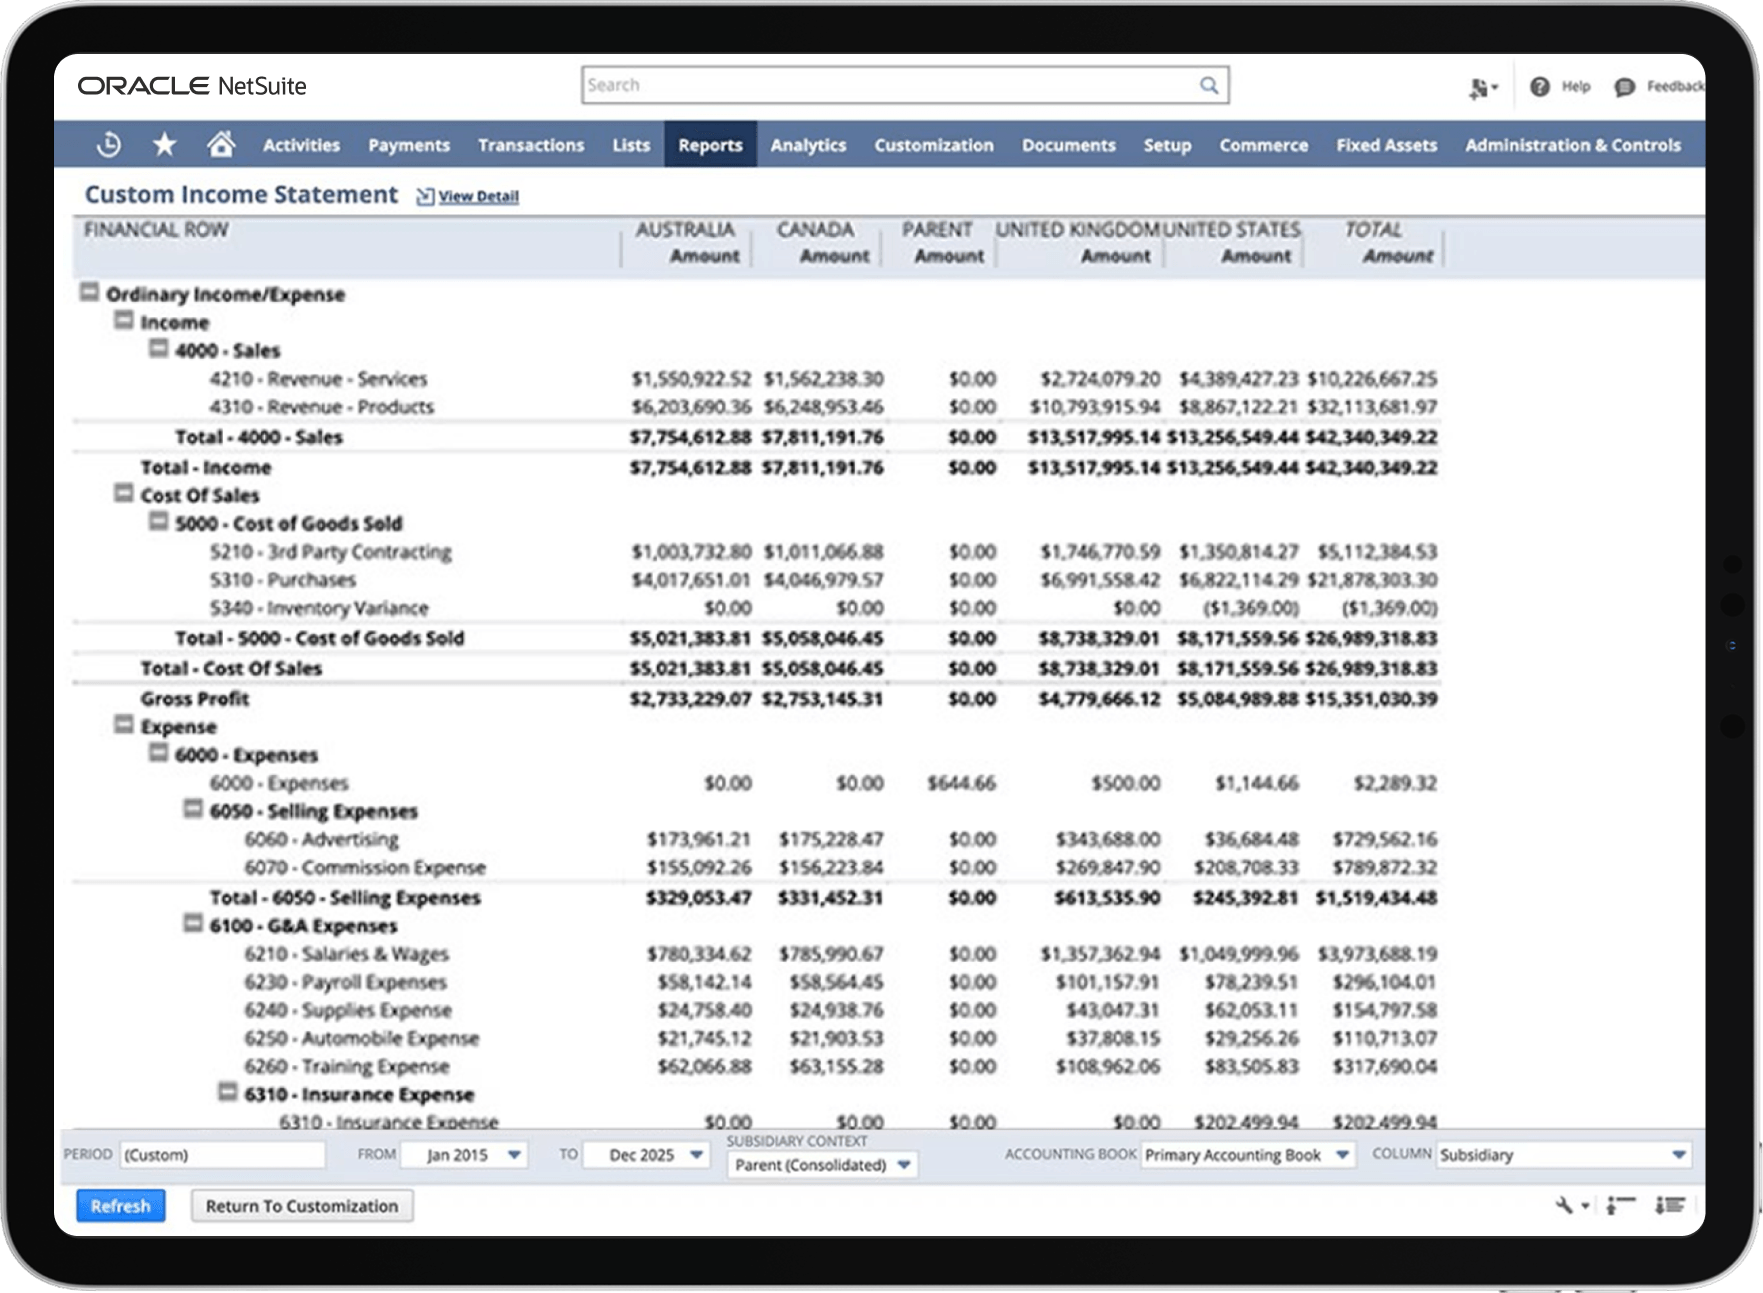
Managing overhead requires visibility, but data scattered among disconnected systems creates blind spots and delays that compound as a business grows. NetSuite Manufacturing ERP Software integrates financials, inventory, demand planning and reporting into one cloud platform, giving businesses real-time insights into every cost centre.
Manufacturing ERP software offers deeper insights, layering on production planning, shop floor control and quality management. These systems work together to automate data collection and reporting, while role-based dashboards display key metrics like overhead rate, cost per unit and absorption variances. NetSuite’s AI-powered anomaly detection can identify unusual cost patterns before they erode margins, and its Ask Oracle feature lets finance teams query overhead data conversationally, getting answers without building custom reports. Teams get the visibility they need to control costs, with fewer surprises that eat into margins.
NetSuite’s Financial Dashboard
Manufacturing overhead is a broad cost category that should be part of nearly every pricing, profitability and operational decision. Understanding and tracking indirect costs helps manufacturers shine a light on inefficiencies before they drain profits, and set prices that protect margins. In the UK, overhead pressures like rising employer NICs and volatile energy costs make effective overhead cost management essential for staying competitive.
Manufacturing Overhead FAQs
What is an example of manufacturing overhead?
A common overhead cost is factory utilities, such as the electricity and gas that powers equipment and lighting. These costs are necessary for production but aren’t linked to individual products and are therefore classified as overhead.
Why is manufacturing overhead important?
Overhead is typically a significant component of a manufacturer’s total costs. If a manufacturer doesn’t track its overhead, it risks underpricing products and missing operational inefficiencies that drag down margins. Proper overhead management also supports reliable forecasting and budgeting.
How is manufacturing overhead applied?
Overhead is typically applied using a predetermined overhead absorption rate (OAR). This rate is calculated by dividing total overhead by a chosen allocation base, such as direct labour hours or machine hours, and then multiplying OAR by the base required to produce each unit, such as hours to produce one table.
Is manufacturing overhead an asset?
Overhead is not an asset on its own. However, on the balance sheet, it is usually absorbed into the cost of finished goods and becomes part of inventory value until those goods are sold. Once products are sold, overhead is transferred to cost of sales in the profit and loss account.
What contributes to manufacturing overhead?
Common overhead sources include indirect labour (supervisors, maintenance staff), indirect materials (lubricants, cleaning supplies), utilities, rent, business rates, equipment depreciation, maintenance costs, regulatory compliance expenses and insurance.